Annuity Factor
The annuity factor definition is the use of a financial method that shows the value, present or future, of an amount when it is multiplied by a periodic amount. The calculation of an annuity factor requires the number of years involved, or the periodic amount, and the percentage rate applicable. The most often used for annuity factors are investments with either or both an annual payment or return. Typical examples of annuity factors being applied are savings accounts, certain types of insurances, or retirement savings plans.
The annuity factor meaning is a particular type of accumulating discount factor used to determine the present or future value of annuities, as well as equated installments. Another name for annuity factors is the annuity formula, and we’ll get into that momentarily.
The Present Value Annuity Factor
The present value annuity factor allows you to determine the amount of money required at the present time in order to result in a future series of payments assuming a fixed interest rate is applied.
In order to reach the present value annuity factor, a formula is used that discounts a future value amount to the present value amount through the use of the applicable interest rate. The period of time during which the investment will last is also taken into account to reach the correct value.
The Present Value Annuity Formula
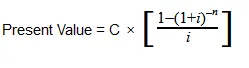
With:
C=cash flow per period
i = interest rate
n = number of payments
The Future Value Annuity Factor
The future value annuity factor gives access to the final return value of a series of regular investments taking into account their worth at a future time, usually at the end of the investing period, assuming that a fixed interest rate is applied.
To reach the future value annuity factor, the formula above is slightly altered in order to add the values collected over the years by also accounting for the set interest rate.
The Future Value Annuity Factor
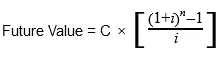
With:
C=cash flow per period
i = interest rate
n = number of payments
Applying the Annuity Factor formulas:
Considering an investment with an annual $2,000 payment over the course of five years at an interest rate of 5%, let’s see what the present and future value would be.
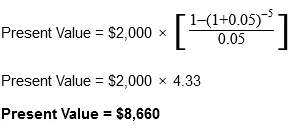
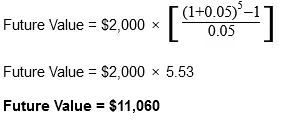
The previous formulas can help you determine the present and future values of ordinary annuities. While the math might seem complicated, there are financial calculators online that can help you out with the correct inputs and data.
Popular Real Estate Terms
When a real estate company switches from one accounting method to another. ...
In legal terms, the definition of null and void (“void ab initio”) can describe an agreement that has no force or binding power. Therefore, it’s neither valid nor legally ...
Husband's common law rights to the property his deceased wife owned either during the marriage or at the time of her death. The husband has life estate rights in the deceased wife's ...
Provision in a lease agreement in which the lessee is given the right to buy the property at the end of lease term. In many cases, the option price is attractive to encourage acquisition. ...
Owner of land allowing another to use space under the ground, such as to install a sewer or gas line. ...
Outline or diagram of a structure or group of structures used for planning purposes. ...
Landlord's right to receive the value of the tenant's property to pay for unpaid rents or for damages to the leased premises. ...
revising the terms of a loan such as when the borrower is experiencing severe financial difficulties. For example, a homeowner lost his job and seeks relief by requesting the lender ...
Risk involved when a potential buyer or seller of property decides not to buy or sell. For example, if a seller does not sell at the offered price, he runs the risk of not being able to ...
Have a question or comment?
We're here to help.