Mortgage Amortization
Definition of "Mortgage Amortization"

The term mortgage amortization is the steady switch occurring to each mortgage payment between how much interest is covered and how much principal each month. Simply put, mortgage amortization is the plan for repaying a mortgage. Because the debt diminishes with each payment, the interest diminishes, and because the interest decreases monthly, the principal coverage increases with each payment.
The Mortgage Amortization Definition
Amortization is the way through which mortgages are repaid. This feature can be applied to mortgages with an equal monthly payment and a fixed timeline. Mortgages, as well as other loans, can be amortized.
Let’s see this through a more practical explanation. The trademark of an amortized mortgage or amortized loan is the shift from paying mostly interest every month to mainly paying principal every month. The math goes like this: for a $100,000 mortgage with a 4.5% interest rate, amortized over a span of 30 years, the fixed monthly payment totals at $507. In this value, during the first month, we will see that $375 goes to cover the interest, and the remaining $132 covers the principle. Towards the mortgage’s mid-term, there is a switch with $249 going to the interest and $257 to the principle. The last mortgage payment will be split into $2 for the interest and $505 for the principal.
How does Mortgage Amortization work?
Mortgage amortization is a repayment plan that uses an amortization table or amortization schedule as a way to visualize the concept. An amortization schedule is a grid or table showing how payments are split between the interest and the principal, and the balance that remains after each payment. Below you can see how mortgage amortization works in time.
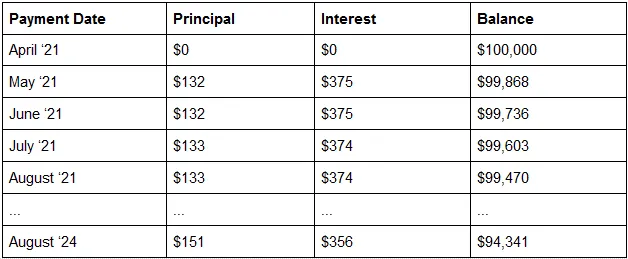
With mortgage amortization, after four payments, the balance reaches $99,470, and in 3 years, the balance is $94,341. An amortized mortgage is a loan where the balance decreases gradually at first and more abruptly in the final years. Similarly, equity is built slowly at first but more rapidly in the last years.
Popular Real Estate Terms
Branch of economics that is concerned with the study of factors that explain, and policies that promote, regional economic growth and development. Regional economic factors affect ...
Surveyor's use of hypothetical lines to portray a properties position. North to South in the meridian line while East to West is the base line. ...
(1) Civil: Individual against whom a court action is brought by a plaintiff for restitution of property or satisfaction of a complaint. (2) Criminal: Individual accused of a crime such ...
A narrow passageway between buildings providing secondary rear access. ...
A rental contact in which the tenant's rental is tied to a change in the price level, such as the Gross National Price Deflator. ...
Document, such as a deed, which demonstrates property ownership. ...
Actual notice to one or more individuals to cease and desist from performing a particular action. For example, a homeowner begins constructing several new rooms onto an existing house ...
Typically, the legal term attachment refers to seizing a person’s property, being charged with debt, and giving it to the wronged creditor until the process is in motion. Attachment ...
principal line running north and south in the government rectangular survey method. Other meridians, each 24 miles apart, are surveyed from the principal meridian. ...
Have a question or comment?
We're here to help.